
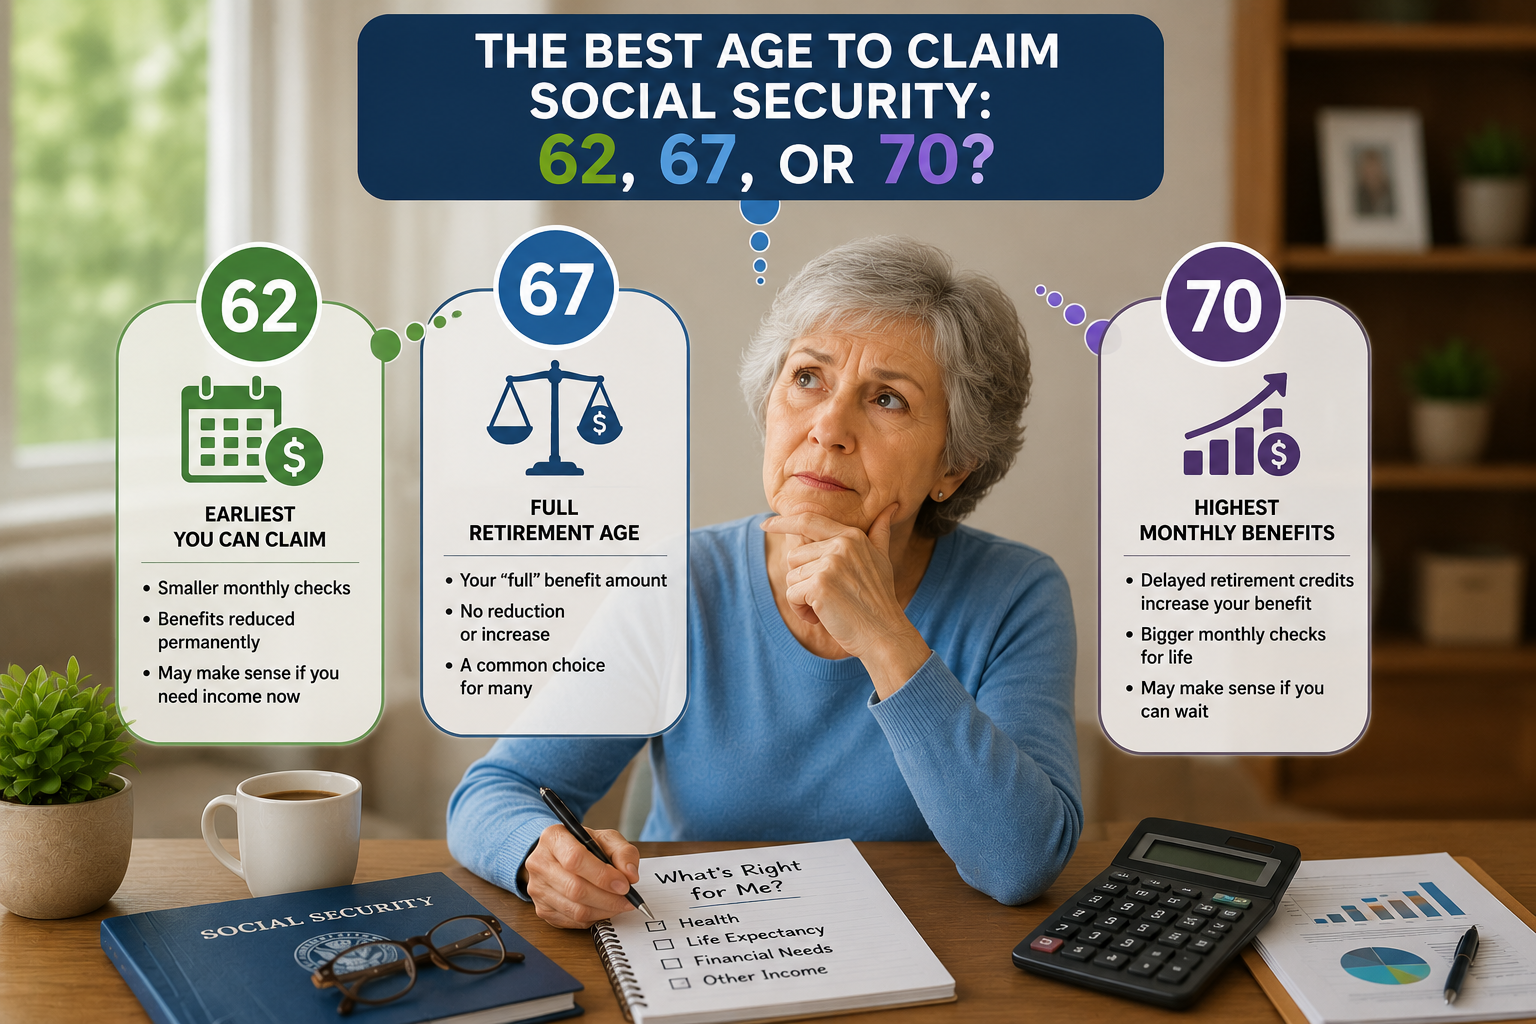
One of the biggest financial decisions many Americans will ever make is deciding when to claim Social Security. It may seem like a simple choice. After all, you can start collecting benefits at age 62, wait until your full retirement age of 67 if you were born in 1960 or later, or delay until age 70 for even larger monthly payments. However, this decision can affect your finances for the rest of your life.
Every year, millions of Americans face this question. Some people claim benefits as soon as they become eligible because they need the money immediately. Others wait because they want larger monthly checks. There is no single answer that works for everyone because health, savings, work status, family situation, and life expectancy all play important roles.
According to recent Social Security data, many Americans still claim benefits before reaching full retirement age, even though doing so permanently reduces their monthly payments. At the same time, only a small percentage wait until age 70, despite the fact that waiting can significantly increase monthly benefits.
The good news is that understanding the advantages and disadvantages of each age can help you make a better decision. Before rushing to claim benefits, it is important to understand what happens at ages 62, 67, and 70 and how each option could affect your long-term financial security.
Claiming Social Security at Age 62: Why Many People Choose the Earliest Option
Age 62 is the earliest age most Americans can begin collecting Social Security retirement benefits. For many people, this option is attractive because it provides immediate income. Someone who retires early, loses a job, develops health problems, or simply needs financial support may feel that waiting is not realistic.
The biggest advantage of claiming at 62 is obvious. You start receiving money sooner. This can help people who have little savings, unexpected medical expenses, or other financial obligations. For some households, the income is necessary for day-to-day living.
However, the trade-off is significant. If your full retirement age is 67, claiming at age 62 can reduce your monthly benefit by about 30% for the rest of your life. In other words, you receive smaller monthly checks permanently because you started collecting benefits earlier.
Many retirees do not fully appreciate how long this reduction lasts. Five years may not seem like a long time when making the decision, but the lower payment can affect your finances for decades. If you live into your 80s or 90s, the difference between claiming at 62 and waiting longer could amount to tens of thousands of dollars.
Claiming at 62 can make sense for people with serious health concerns, shorter life expectancy, or an immediate need for income. But it is important to understand that the lower monthly benefit is generally permanent. That is why experts often encourage people to examine their financial situation carefully before choosing the earliest claiming age.
Claiming Social Security at Age 67: The Full Retirement Age Option
For people born in 1960 or later, age 67 is considered full retirement age. This is the age at which you can receive your full Social Security retirement benefit based on your earnings history. Unlike age 62, there is no permanent reduction for claiming at full retirement age.
Many financial planners consider age 67 a balanced option. You avoid the large reduction that comes with claiming at 62, but you do not have to wait until age 70 to start receiving benefits. For many retirees, this creates a middle ground between receiving income now and maximizing future benefits.
Another advantage of reaching full retirement age is that the Social Security earnings limit no longer applies. People who continue working after full retirement age can earn as much as they want without having benefits reduced because of work income.
Recent Social Security data shows that a large percentage of Americans claim benefits around their full retirement age. Many see it as the safest and most predictable option because it provides the benefit amount they earned throughout their working career without any early retirement penalties.
For people who have enough savings to bridge the gap between retirement and age 67, waiting until full retirement age can provide a stronger financial foundation than claiming early. However, there is still one more option that may provide even larger monthly checks.
Claiming Social Security at Age 70: The Largest Monthly Check Available
Age 70 is the latest age at which delaying Social Security provides additional financial rewards. Every year you delay benefits after reaching full retirement age, Social Security increases your future monthly payment through delayed retirement credits. For most people born after 1943, these credits increase benefits by approximately 8% per year until age 70.
For someone whose full retirement age is 67, waiting until age 70 can increase their monthly benefit to approximately 124% of their full retirement age benefit. In simple terms, waiting three additional years can result in a roughly 24% larger monthly payment.
This larger benefit continues for the rest of the retiree’s life. Future COLA increases are also applied to the larger amount, meaning the advantage can grow over time.
The downside is obvious. You must wait longer before receiving any benefits. For people who need income immediately or who have health concerns, waiting until 70 may not be practical. In fact, only a relatively small percentage of Americans delay benefits until age 70.
Still, for healthy individuals with adequate savings and a family history of longevity, waiting until 70 can provide substantial long-term financial benefits. It may also increase survivor benefits available to a spouse after death, making it particularly attractive for married couples.
So, What Is the Best Age to Claim Social Security?
The truth is that there is no universal “best age” for everyone. The right choice depends entirely on your personal circumstances. Someone with health challenges and limited savings may benefit from claiming earlier. Someone in good health with strong retirement savings may benefit from waiting longer.
If your primary goal is receiving money as soon as possible, age 62 may make sense. If you want your full earned benefit without waiting until 70, age 67 offers a balanced approach. If your goal is maximizing monthly income for life and you can afford to wait, age 70 usually provides the highest monthly benefit available.
The decision should not be based solely on what friends, neighbors, or family members did. Every retirement situation is different. Factors such as health, expected lifespan, work plans, savings, marital status, taxes, and future income needs all matter.
Before claiming Social Security, it is worth reviewing your estimated benefits through your Social Security account and comparing what you would receive at ages 62, 67, and 70. A few extra years of waiting could mean hundreds of dollars more each month. On the other hand, taking benefits earlier may be the right choice if it provides financial stability when you need it most.
The best age to claim Social Security is not necessarily the earliest age or the latest age. It is the age that best fits your financial needs, health situation, and retirement goals.
