
For millions of Americans, Social Security is one of the most important sources of income during retirement. Many retirees depend on their monthly benefits to help pay for housing, food, healthcare, transportation, and everyday expenses. While Social Security provides valuable financial support, many people make costly mistakes when claiming or managing their benefits. These mistakes can reduce lifetime income by thousands, and in some cases even tens of thousands, of dollars.
One of the biggest challenges is that Social Security rules can be complicated. Decisions about when to claim benefits, whether to continue working, how spousal benefits work, and how taxes affect payments are often confusing. Many retirees make decisions based on incomplete information or advice from friends and family who may not fully understand the system themselves.
The impact of a Social Security mistake often lasts for the rest of a person’s life. Unlike some financial decisions that can easily be corrected, many Social Security choices are permanent. A decision made at age 62 could affect benefit payments for decades. That is why understanding common mistakes is so important.
In recent years, rising living costs, healthcare expenses, and inflation have made Social Security benefits even more valuable. Every dollar matters when retirees are living on fixed incomes. Unfortunately, many people unknowingly leave money on the table simply because they fail to understand how the system works.
By learning about the most common Social Security mistakes, future retirees can make more informed decisions and maximize the benefits they have earned through years of work. Understanding these pitfalls can help protect retirement income and improve financial security throughout retirement.
Claiming Benefits Too Early Without Understanding the Consequences
One of the most common Social Security mistakes is claiming benefits as soon as eligibility begins at age 62. While it can be tempting to start receiving monthly payments early, many retirees do not fully understand how much this decision can reduce their benefits.
Social Security allows workers to begin collecting retirement benefits at age 62, but doing so results in a permanent reduction in monthly payments. Full Retirement Age varies depending on the year of birth, but for many current retirees it falls between ages 66 and 67. If benefits are claimed before reaching Full Retirement Age, monthly payments can be reduced by as much as 30%.
For example, a worker entitled to $2,000 per month at Full Retirement Age may receive only about $1,400 if benefits begin at age 62. That reduction continues for life. Over a retirement lasting 20 or 30 years, the total loss can amount to tens of thousands of dollars.
Many people choose early retirement because they need income immediately or are concerned about their health. In some situations, claiming early may make sense. However, many retirees simply assume taking benefits early is always the best option without considering their long-term financial needs.
Another factor is longevity. Americans are living longer than previous generations. Someone who lives into their 80s or 90s may receive significantly more lifetime income by delaying benefits rather than claiming early. The longer a person lives, the more valuable delayed benefits become.
Before making a claiming decision, retirees should carefully evaluate their health, financial resources, employment plans, and expected retirement expenses. Rushing to claim benefits without understanding the long-term consequences remains one of the most expensive Social Security mistakes people make.
Failing to Delay Benefits for Higher Monthly Payments
While claiming benefits too early can reduce retirement income, another costly mistake is failing to understand the advantages of delaying Social Security beyond Full Retirement Age.
Social Security rewards workers who delay claiming benefits. For every year benefits are postponed after Full Retirement Age, monthly payments increase through delayed retirement credits. These credits continue until age 70. Depending on a person’s circumstances, delaying benefits can increase monthly payments by approximately 8% per year.
The difference can be substantial. A retiree eligible for $2,500 per month at Full Retirement Age could potentially receive more than $3,100 per month by waiting until age 70. That higher payment lasts for life and may also increase survivor benefits for a spouse.
Many retirees focus only on getting money as soon as possible rather than maximizing lifetime income. They may worry about whether they will live long enough to benefit from delaying. While nobody can predict the future, delaying often provides valuable protection against longevity risk—the possibility of living longer than expected.
Larger monthly payments can also help retirees cope with future inflation and rising healthcare costs. Because annual Cost-of-Living Adjustments are based on the size of existing benefits, higher starting payments generally result in larger future increases.
Couples can particularly benefit from strategic claiming decisions. In many cases, delaying benefits for the higher-earning spouse can significantly improve household income and provide larger survivor benefits if one spouse dies.
Of course, delaying is not appropriate for everyone. Some retirees have health issues or financial circumstances that require earlier benefits. However, many people fail to consider delaying simply because they do not understand how much additional income it can generate over time. This lack of planning often leads to lower retirement income throughout their later years.
Ignoring How Working Can Affect Benefits
Many retirees choose to continue working after claiming Social Security. While working during retirement can provide valuable income, misunderstanding Social Security earnings rules can create costly surprises.
If a person claims Social Security before reaching Full Retirement Age and continues working, benefits may be temporarily reduced if earnings exceed annual limits. Many retirees are shocked when they discover their Social Security payments have been reduced because they earned more than expected from employment.
For workers under Full Retirement Age, Social Security applies an earnings test. Benefits are reduced when earnings exceed a specific annual threshold. While the withheld benefits are not permanently lost, the temporary reduction can affect cash flow and retirement planning.
Some people mistakenly believe they should stop working entirely to avoid affecting Social Security. Others claim benefits early without understanding how employment income could reduce payments. Both decisions can result in financial inefficiencies.
Another important consideration involves payroll taxes and future benefits. Continuing to work may increase future Social Security payments if additional earnings replace lower-earning years in a worker’s earnings history. Social Security calculates benefits using a person’s highest 35 years of earnings. Higher-income years can potentially increase future benefits.
Many retirees also overlook the tax implications of combining Social Security with employment income. Depending on total income levels, a portion of Social Security benefits may become subject to federal income taxes.
Understanding how work and Social Security interact is essential for retirees who want to maximize income. Before claiming benefits, individuals should carefully review earnings limits, tax considerations, and the potential impact of continued employment. Failing to do so can result in unexpected reductions and costly mistakes that affect overall retirement finances.
Overlooking Spousal and Survivor Benefits
Many married couples make the mistake of focusing only on individual retirement benefits while overlooking valuable spousal and survivor benefits available through Social Security.
Spousal benefits allow eligible spouses to receive benefits based on their partner’s earnings record. In some situations, a spouse may qualify for a larger payment through a spousal benefit than through their own work history. However, many couples fail to explore these options and miss opportunities to increase household income.
Survivor benefits are even more important. When one spouse dies, the surviving spouse may be eligible to receive benefits based on the deceased spouse’s earnings record. Strategic claiming decisions can significantly affect the size of future survivor benefits.
For example, when a higher-earning spouse delays benefits until age 70, the resulting larger benefit can later provide greater financial protection for a surviving spouse. Many couples do not realize that claiming decisions made today can affect survivor income years into the future.
Divorced individuals may also qualify for benefits based on a former spouse’s earnings record if certain requirements are met. Unfortunately, many divorced retirees never investigate whether they qualify for these benefits.
The rules governing spousal and survivor benefits can be complex, but they can provide significant financial advantages. Ignoring these opportunities often results in lower lifetime income and reduced financial security.
Couples approaching retirement should evaluate Social Security as a household decision rather than an individual one. Understanding how various claiming strategies affect both spouses can help maximize total lifetime benefits and provide better protection against financial challenges later in retirement.
Failing to Understand Social Security Taxes and Benefit Calculations
Another costly mistake involves misunderstanding how Social Security benefits are taxed and calculated. Many retirees assume their entire benefit will be tax-free, only to discover that a portion may be subject to federal income taxes.
Depending on combined income levels, up to 85% of Social Security benefits may become taxable. Income from pensions, retirement accounts, investments, and employment can affect tax liability. Failing to plan for these taxes can create unexpected financial burdens during retirement.
Many retirees are also unaware of how Social Security calculates benefits. The program uses a worker’s highest 35 years of earnings when determining retirement benefits. Individuals with fewer than 35 years of work history may have zero-income years included in the calculation, reducing benefits.
Some workers retire without realizing that a few additional years of employment could replace low-earning years and increase monthly benefits. Others fail to review their earnings records for errors. Mistakes in earnings records can result in lower benefit calculations if left uncorrected.
Creating a personal Social Security account allows workers to review their earnings history and estimate future benefits. Checking these records periodically can help identify problems before retirement.
Taxes and benefit calculations may seem complicated, but understanding them can prevent costly surprises. Retirees who take time to learn how benefits are calculated and taxed often make better decisions and avoid mistakes that reduce retirement income.
Conclusion: Careful Planning Can Protect Your Retirement Income
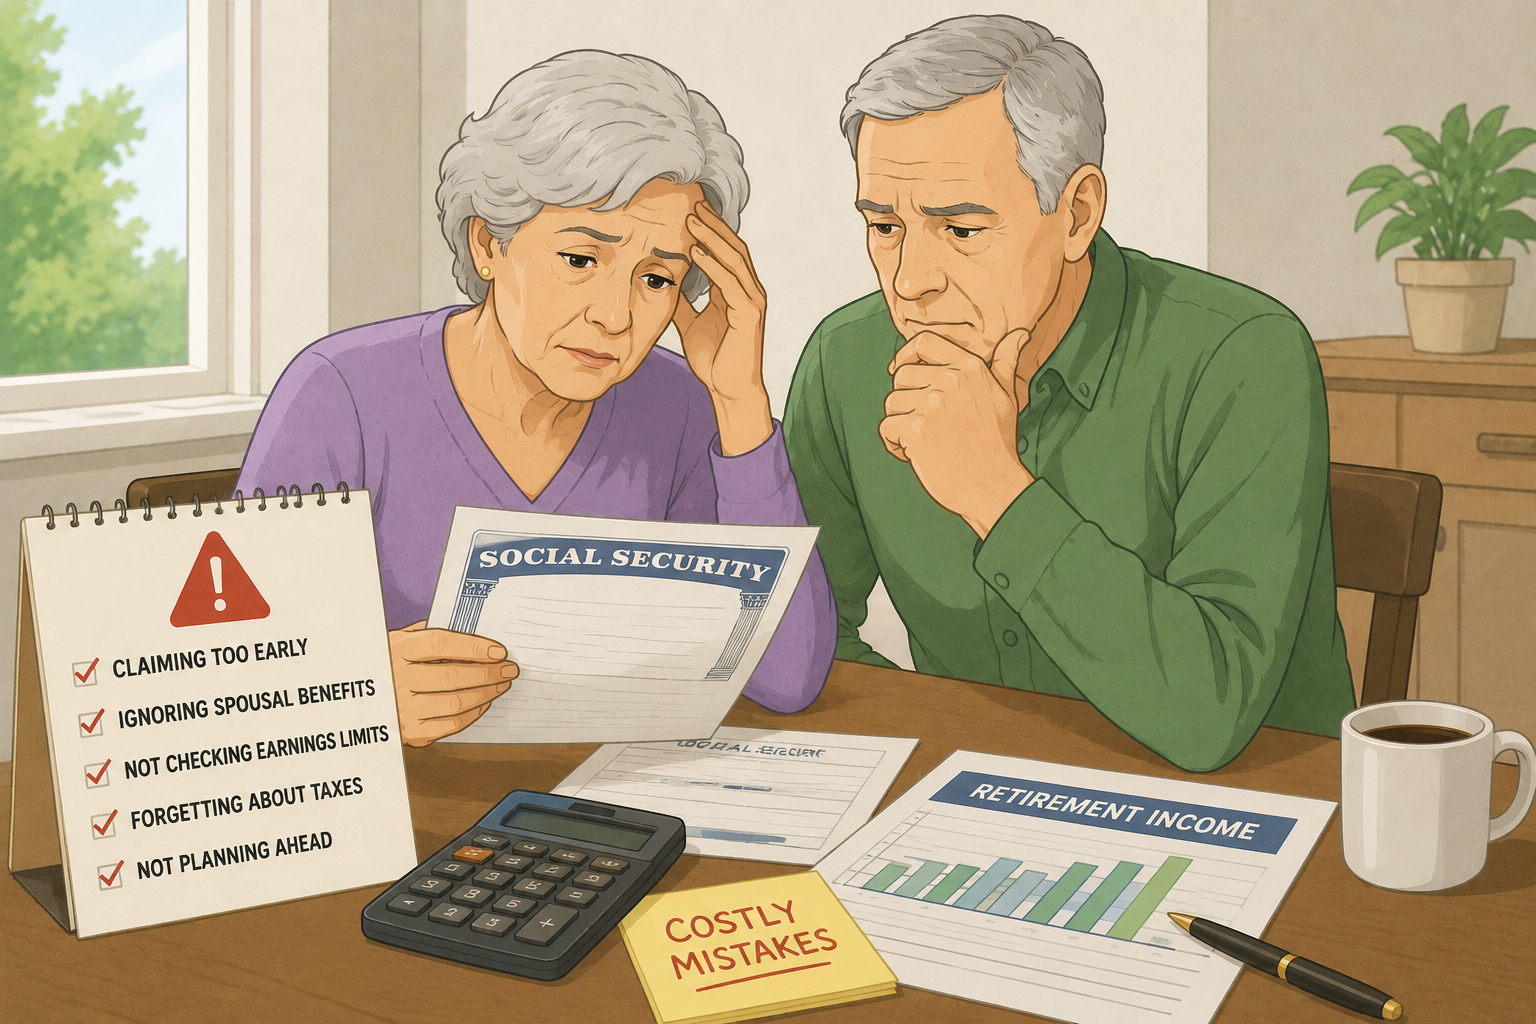
Social Security is one of the most valuable retirement benefits available to American workers. However, many retirees unknowingly make decisions that reduce their lifetime income by thousands of dollars. Claiming benefits too early, failing to delay benefits when appropriate, misunderstanding work rules, overlooking spousal benefits, and ignoring tax implications are among the most common mistakes.
The good news is that many of these errors can be avoided through education and planning. Taking time to understand Social Security rules, reviewing earnings records, evaluating claiming strategies, and considering long-term financial needs can significantly improve retirement outcomes.
As healthcare costs, housing expenses, and inflation continue to rise, maximizing Social Security benefits becomes increasingly important. Every additional dollar of guaranteed retirement income can help provide greater financial security and peace of mind.
Retirement planning is about more than simply deciding when to stop working. It involves making informed decisions that protect income for years or even decades to come. Understanding the most common Social Security mistakes is one of the best ways retirees can safeguard their financial future and make the most of the benefits they have spent a lifetime earning.
